Should You Buy a Home in Lafayette, Colorado?
Lafayette can be a practical choice for buyers who want Boulder County access and a distinct community setting. The right purchase depends on the specific home's condition, location, ongoing costs, and financing fit.
Brandon RearickSeptember 16, 20267 min read
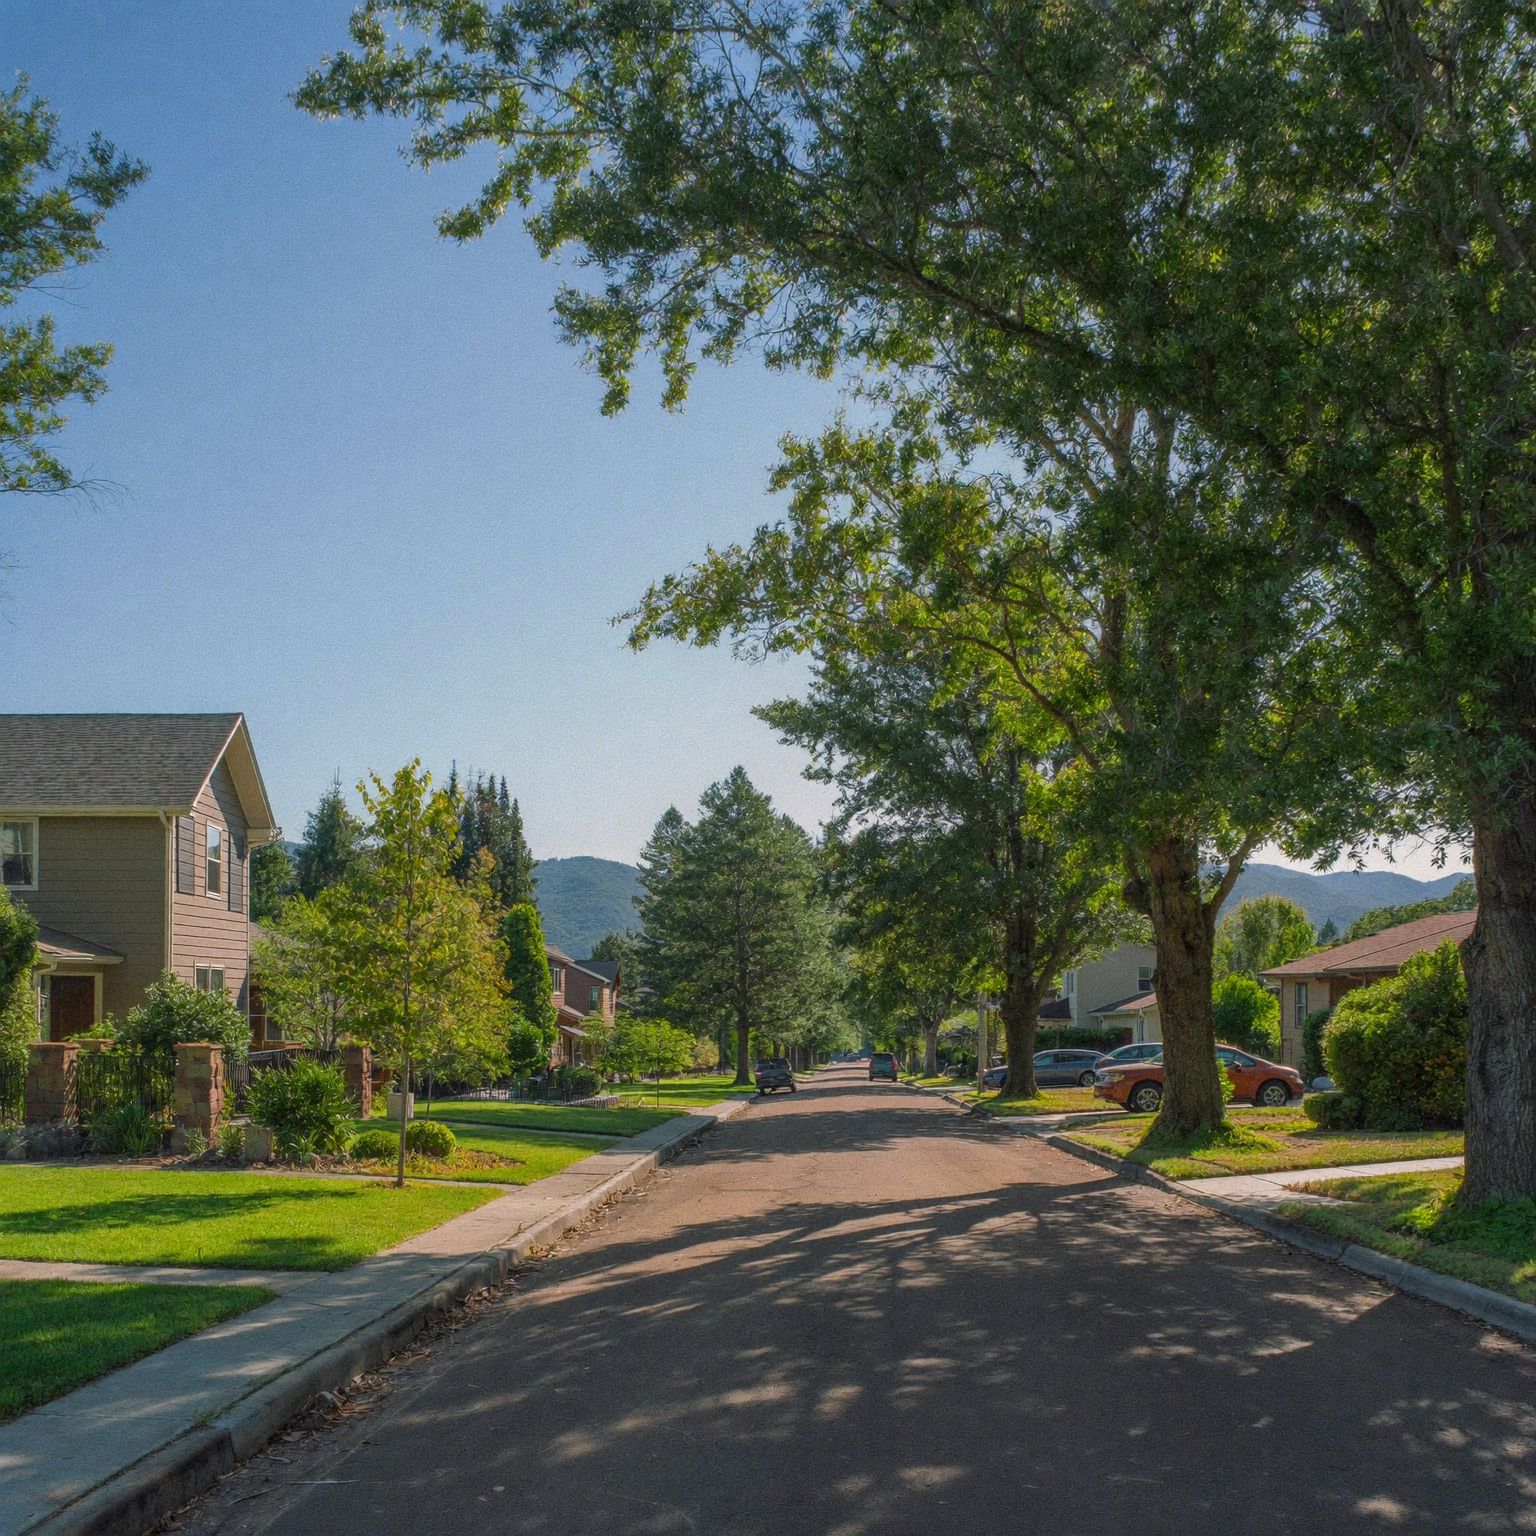
Yes, Lafayette can be a good place to buy if you want access to Boulder County, an established community, and multiple routes toward Boulder and Denver. The decision should come down to the specific address, because home condition, neighborhood design, commute patterns, HOA obligations, and financing can vary significantly across the city.
I would not judge a Lafayette home from its listing photos or asking price alone. Before making an offer, I help buyers evaluate how the property fits their monthly budget, what the physical condition could mean after closing, and whether the location supports their daily routine.
Start with the address, not a general opinion of Lafayette
Lafayette sits in Boulder County, but it is not one uniform housing market. A home near Old Town can offer a different experience from a property in a planned neighborhood, and two houses with similar living areas may have very different lots, renovation histories, HOA rules, and maintenance needs.
Start by mapping the places you will visit regularly. That may include an employer, child care, medical offices, grocery stores, recreation, or family. Then drive from the property during the times you would normally travel. A map estimate cannot show how a school drop-off, a busy intersection, winter weather, or construction will affect your routine.
Buyers can begin with the main Lafayette community page, but the goal should be to narrow the search based on real priorities rather than a generic ranking of neighborhoods.
Is Lafayette a good place to buy a home?
Lafayette is worth considering if Boulder County access, community amenities, and proximity to nearby cities matter to you, but it is not automatically the right fit for every buyer. Some buyers prioritize an older neighborhood with a less uniform streetscape, while others want newer construction, an HOA, neighborhood trails, or more predictable exterior standards. The best test is to compare actual homes and their total ownership obligations rather than deciding based only on the city name.
How do Lafayette neighborhoods differ?
A neighborhood comparison should account for more than architecture. I look at street layout, sidewalks, nearby land uses, parking, lot orientation, HOA documents, exterior maintenance, and the route in and out of the neighborhood.
Old Town Lafayette may appeal to buyers who like an established setting and proximity to local destinations. Older properties, however, deserve careful review for additions, remodels, sewer lines, drainage, electrical systems, and other components that may have changed over time.
A planned neighborhood such as Indian Peaks can present a different ownership structure. Buyers should determine what an association maintains, what architectural restrictions apply, and whether there are rules affecting fences, parking, rentals, landscaping, or future exterior projects.
These are not reasons to favor one area automatically. They are reasons to compare the complete ownership experience. A neighborhood that looks attractive during a showing may not work if the commute is inconvenient, the rules conflict with your plans, or the home's upcoming projects strain your budget.
How should I compare Old Town with a planned neighborhood?
Compare the type of responsibility you are willing to accept. An older home may offer character, a mature setting, and proximity to central Lafayette, but it may also require more investigation into past work and aging systems. A planned neighborhood may provide clearer design standards and shared amenities, but that can come with dues, restrictions, and approval requirements. Review one or two real properties in each setting, including disclosures and HOA materials, before deciding which model fits you.
What should you investigate before making an offer?
Colorado buyers need to separate visible finishes from expensive building components. New flooring and updated counters are easy to notice. Drainage, roofing, sewer condition, foundation movement, electrical capacity, and permit history require more deliberate investigation.
For a Lafayette property, I would consider the following pre-offer questions:
- Does the county or city record align with the home's apparent layout and finished space?
- Were additions, basement finishes, decks, or major remodels permitted when required?
- Does the lot direct water away from the foundation?
- Are there signs of past moisture intrusion or repairs?
- What does the seller's property disclosure reveal?
- Is the property governed by an HOA, and have the current documents been obtained?
- Are there known insurance concerns involving the roof, electrical system, prior claims, or property condition?
- Could a future renovation be limited by zoning, setbacks, easements, or association rules?
These questions do not replace an inspection. They help determine whether the home deserves an offer and whether the contract should provide enough time for proper due diligence. My broader home buying guide explains how these steps fit into the full purchase process.
Should I review permits before offering on an older Lafayette home?
Yes, especially if the property has an addition, converted space, finished basement, structural changes, or substantial remodeling. A permit record does not guarantee perfect workmanship, and a missing record does not by itself prove that work was improper. It gives you another source of information to compare with the listing, seller disclosure, inspection findings, and your intended use of the space. If something material is unclear, consult the appropriate city department or qualified professional before the contract deadlines expire.
Calculate the full cost before focusing on price
The asking price is only one part of the decision. Your monthly housing obligation may include principal, interest, property taxes, homeowners insurance, mortgage insurance, and HOA dues. After closing, you will also be responsible for maintenance and repairs that may not follow a convenient schedule.
With more than 14 years in mortgage lending, I have seen buyers focus on the maximum amount a lender will approve instead of the payment and reserves that make ownership sustainable. Those are not the same calculation. A sound budget leaves room for normal life and for the home's less predictable costs.
Before touring seriously, obtain a documented mortgage pre-approval. Then ask the lender to model the actual property once you identify it. Taxes, insurance, HOA dues, seller credits, down payment, and loan structure can change the cash required and monthly obligation.
A townhouse, detached home, and older property without an association may each shift costs into different categories. HOA dues are visible, but they may cover specific services or shared components. A property without dues can still require the owner to budget independently for every exterior item. Compare what is included, what is excluded, and what you may need to replace.
How much cash should I keep after buying?
Keep enough that closing does not leave you unable to handle moving expenses, an insurance deductible, routine maintenance, or an early repair. The right reserve depends on the property's age and condition, your income stability, and which major systems may need attention. I prefer to evaluate this before writing an offer, because using every available dollar for the down payment or appraisal gap can create avoidable pressure after closing.
Build an offer around the property, not emotion
A strong offer is not necessarily the one with the highest price. The terms should reflect the property's condition, available documentation, your financing, and your tolerance for unresolved risk.
Before recommending an offer structure, I want to know whether the buyer has reviewed the seller disclosures, whether HOA documents are available, and whether there are obvious questions involving condition or permitted use. I also consider the buyer's lending timeline and available cash. Across 76 closed transactions in the last five years, I have found that clear preparation usually matters more than last-minute improvisation.
Contract deadlines deserve attention. Inspection, title, HOA review, appraisal, loan conditions, insurance, and closing logistics can all affect the transaction. Buyers should understand what each deadline controls and what options the contract provides. For a broader explanation of common process questions, review the buyer FAQ.
You can use the current home search to identify possibilities, but do not treat online status or listing remarks as complete due diligence. Availability changes, and material facts should be verified through the listing documents, public sources, inspections, and the appropriate professionals.
Should I waive an inspection to make my offer stronger?
I would not treat an inspection waiver as a standard Lafayette buying strategy. The risk depends on the property's age, visible condition, seller documentation, your financial reserves, and the exact contract language. There may be ways to make terms more focused without giving up the opportunity to learn about the home. Before changing inspection rights, understand what you could be accepting and whether you could afford the consequences.
Verify schools, boundaries, and future plans
If schools affect your decision, verify attendance eligibility for the specific address directly with the school district. Do not rely solely on a listing, map, or third-party real estate website because boundaries and enrollment policies can change.
Also look beyond the current streetscape. Review nearby parcels, major roads, trails, commercial areas, and visible vacant land. If a future land use is important to your decision, ask the relevant local authority for current information. A seller, agent, or neighbor may provide useful context, but they cannot guarantee what will happen later.
What is my best first step if I want to buy in Lafayette?
Define your comfortable monthly obligation, complete a documented pre-approval, and list the location and property features that are truly necessary. Then compare homes in at least two Lafayette settings so you can see how age, HOA structure, lot design, and access affect the decision. Once you find a serious candidate, investigate that address before writing terms. That sequence keeps the search focused and helps prevent an attractive listing from pushing you beyond your financial or practical limits.
Related Articles
- What Does a $5,000 Closing Cost Credit Cover?A $5,000 closing cost credit can reduce many of the lender, title, insurance, tax, and prepaid expenses due at closing. Its actual value depends on the source of the credit, your loan terms, and your eligible costs.
- How to Buy New Construction in Northern Colorado Without Getting BurnedBuying new construction in Northern Colorado? Learn what builder contracts really say, how to negotiate incentives, and why independent representation costs you nothing.
- Colorado Home Buyer Closing Costs: How Much Cash Do You Really Need at Closing?Learn what Colorado home buyers should budget for at closing, including cash to close, closing costs, prepaids, seller credits, and common mistakes to avoid.